Insight Partners Co-Head Devin Parekh Discusses AI Realities, Fund Liquidity, and Venture Capital Strategy at StrictlyVC New York

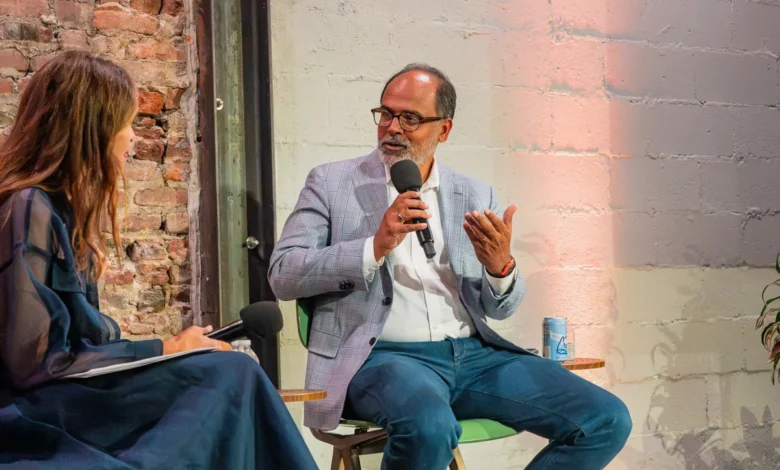
In the high-stakes, hyper-vocal ecosystem of modern venture capital, Devin Parekh represents a distinct archetype of longevity and restraint. Having co-run heavyweight investment firm Insight Partners for 26 years, Parekh has steered the institution through multiple macroeconomic cycles, dot-com bubbles, and financial crises without succumbing to the performative social media presence characteristic of many contemporary tech investors. On a Thursday evening in New York City, sitting down with TechCrunch at the StrictlyVC event, Parekh offered a refreshingly candid assessment of the venture landscape. His remarks spanned the firm’s strategic wins, such as early positions in Databricks and subsequent stakes in foundational AI giants OpenAI and Anthropic, alongside missed opportunities like buzzy legal-tech firm Legora, structural conflicts of interest, and the macroeconomic realities dictating modern technology investments.
Background and Context of the StrictlyVC Gathering
The StrictlyVC event, a premier fixture on the East Coast technology and startup circuit, convened founders, investors, and enterprise leaders in New York to dissect the rapid maturation of the venture economy. Set against a backdrop of historic capital concentration in artificial intelligence, surging private valuations, and a slowly thawing exit environment, the gathering served as a sounding board for top-tier capital allocators. Parekh’s presence underscored Insight Partners’ massive footprint—commanding approximately $90 billion in assets under management (AUM)—and provided a rare public window into the operational calculus of one of the world’s most influential software-focused private equity and venture capital firms.
Navigating the AI Frontier: Risks Versus Transformative Utility
A central theme of the dialogue addressed the mounting cultural and existential anxieties surrounding artificial intelligence. Amid a turbulent news cycle dominated by high-profile safety researcher departures warning of unregulated, self-improving systems, Parekh adopted a pragmatic risk-reward framework. While acknowledging the theoretical hazard of bad actors exploiting open-source models to synthesize biological threats, he argued that the probability distribution heavily favors humanity via accelerated scientific and medical breakthroughs.
Drawing from his governance experience as a board member at NYU Langone Health, Parekh highlighted how machine learning algorithms already parse tens of millions of patient records to identify latent health risks—such as predicting a 25-percent probability of a cardiac event years before clinical manifestation in routine visits. Proponents of this view argue that as global populations age and medical staffing shortages intensify, technological leverage is no longer optional; it is an absolute societal necessity. Parekh likened the risks of generative artificial intelligence to the historical disruptions introduced by next-generation drone warfare or other dual-use technologies, emphasizing that human society has consistently adapted while systematically raising baseline living standards across centuries.
Quiet Performance Versus Loud Public Posturing
Operating a firm with $90 billion in capital necessitates a deliberate communication strategy. While many contemporary venture capitalists project omnipresence across digital platforms and podcasts—frequently opining on complex geopolitical conflicts or macroeconomic indices far outside their core competencies—Insight Partners has consciously chosen a low-profile posture.
Parekh articulated a philosophy rooted in institutional humility: the firm believes its portfolio should generate the primary narrative. While acknowledging the baseline necessity of brand recognition for founder recruitment, Parekh emphasized that sustainable performance must derive from portfolio execution rather than media saturation. This ethos has allowed Insight Partners to quietly build a dominant software portfolio spanning early-stage ventures, growth rounds, and complex buyout transactions.
Chronology and Evolution of Investment Strategy
Insight Partners maintains a dynamic, temporal approach to asset allocation rather than a rigid geographic or structural formula. Analyzing the firm’s historical trajectory reveals fluid shifts across early-stage, growth-stage, and buyout buckets driven entirely by market conditions.
In the wake of sustained high interest rates, restrictive debt capital markets for enterprise software, and compressed public exit multiples, Insight has fundamentally altered its deployment cadence. The firm has notably abstained from executing major buyout transactions since 2024, citing unattractive pricing parameters. Conversely, venture-stage valuations have experienced a resurgence reminiscent of the frothy market dynamics of 2021—a historical parallel that induces caution among seasoned investors.
Under normal market conditions, follow-up investment rounds are justified by accumulated empirical data, allowing investors to pay higher prices for reduced operational risk. However, current top-tier venture rounds move at a velocity that bypasses incremental data collection, forcing funds to pay premiums without mitigating underlying risks. Insight’s logical structural response has been to pivot earlier into the capital stack. By leveraging its scale fund architecture to write modest initial checks—ranging from $20 million to $25 million rather than speculative $500 million tickets—the firm retains the dry powder necessary to aggressively double down on proven winners. This strategy catalyzed massive returns in security platform Wiz, where an initial Series A check was compounded through successive investments, ensuring that any single failure would create negligible friction for a fund of Insight’s magnitude.
Geographic Dispersion and the Evolution of Global Talent
The geography of venture capital has undergone a structural decentralization, even as specific technology verticals remain fiercely concentrated. Parekh noted that technical talent has dispersed globally, pointing to Insight’s aggressive pursuit of Swedish legal-tech company Legora. Although Insight’s leadership flew to Stockholm to pitch the founder, the firm ultimately lost the deal to General Catalyst—an outcome Parekh attributed to competitor sales execution rather than geographic disadvantage.
Nevertheless, the physical geography of compute and foundational architecture remains stubbornly anchored in the San Francisco Bay Area. Infrastructure-heavy artificial intelligence demands a hyper-dense talent ecosystem that continues to draw young investors and engineers to Northern California. Conversely, vertical application software exhibits distinct geographic clustering aligned with target industries—such as financial technology talent concentrating heavily in New York City. Consequently, application-layer and vertical AI investments permit significantly greater geographic diversification than pure foundational infrastructure plays.
Managing Conflicts of Interest in Dual Investments
The contemporary venture capital landscape has broken historical taboos regarding portfolio exclusivity, most notably evidenced by firms backing direct rivals. Insight Partners holds financial stakes in both OpenAI and Anthropic, a dual-exposure strategy that once would have triggered severe governance conflicts.
Addressing internal deliberations, Parekh clarified that the debate centered primarily on investment timing and fund stage rather than moral or strategic contradictions. Early-stage investors—such as Khosla Ventures with OpenAI’s Series A—are inherently bound by board seats and governance duties that preclude investing in direct competitors. However, at later stages of capital formation, when funds operate off the board without controlling strategic governance, purchasing shares resembles acquiring public equities in competing industry titans.
Insight categorized OpenAI as the dominant consumer-facing ecosystem play while identifying Anthropic as an enterprise-grade powerhouse—a dichotomy that continues to evolve dynamically. As these foundational model developers require capital injections scaling from $30 billion to $100 billion per tranche, traditional notions of exclusivity have dissolved under the sheer weight of capital requirements. Nevertheless, at earlier Series A and B junctures, Insight maintains rigorous information-sharing firewalls and strict prohibitions against funding directly competing entities, mindful of founder sensitivities even regarding marginal revenue overlap.
The Debate Over Physical AI and Robotics
While software and foundational models dominate venture inflows, physical artificial intelligence and embodied robotics represent an emerging frontier. Insight Partners has maintained a watchful stance, classifying most robotics and physical intelligence companies as sophisticated science projects. The underlying thesis rests on macroeconomic timing: investors are currently forced to make a speculative bet on whether broad robotics adoption will occur, layered on top of a secondary bet regarding precisely when commercial viability will materialize. While acknowledging generational divergences in perspective—noting that younger investors view physical hardware as the paramount frontier—Insight remains disciplined, preferring to observe market maturation before committing institutional capital.
Concentration Risk and LP Dynamics in Modern Venture Capital
The first half of the year witnessed an extraordinary concentration of venture capital, with foundational model giants OpenAI and Anthropic capturing approximately half of all deployment dollars globally. This unprecedented allocation concentration has sparked acute anxiety among Limited Partners (LPs) regarding portfolio exposure.
Insight Partners avoids excessive concentration, prioritizing historical diversification across thirteen successive flagship funds. However, Parekh acknowledged a bifurcated LP market where emerging venture funds market themselves explicitly around hyper-concentration, allocating 35 to 40 percent of a total fund into a single private entity. While acknowledging that outlier firms like Founders Fund and Thrive Capital have executed concentrated strategies with exceptional returns, Parekh cautioned that historical empirical data over long-term horizons consistently rewards portfolio diversification.
The Crucial Imperative of Liquidity and DPI
A paramount friction point in the current private markets ecosystem is the divergence between paper valuations and realized liquidity. A multitude of first- and second-time venture funds that raised immense capital between 2021 and 2023 have failed to return meaningful capital to their LPs. Consequently, many emerging managers face severe headwinds in raising subsequent fund vintages because they failed to prioritize liquidity mechanisms.
Parekh emphasized that Distributed to Paid-In Capital (DPI) remains the ultimate validation of venture performance. Even when evaluating generational winners projected to appreciate substantially, fund managers have a fiduciary obligation to de-risk positions and return capital to investors. Reflecting on Insight’s own institutional evolution, Parekh noted that the firm previously fell into the psychological trap of holding winning assets indefinitely. Over the preceding two years, however, Insight successfully returned over $20 billion to its LPs via strategic secondary sales and initial public offerings, proving that disciplined liquidity management is essential regardless of fund scale.
Valuation Realities and the Public Market Horizon
As venture capitalists and founders navigate historic private valuations, industry figures like Elad Gill have repeatedly warned of narrow temporal windows—spanning six to twelve months—where private companies achieve peak valuations, urging founders to execute partial liquidity events. Parekh confirmed that Insight continually engages portfolio founders on valuation de-risking, advocating for tactical secondary sales to lock in returns ahead of inevitable market corrections. Compounding multi-billion-dollar valuations at aggressive growth rates over condensed timelines defies mathematical sustainability, necessitating proactive risk management.
Looking toward the macroeconomic horizon, the anticipated public market debuts of industry heavyweights such as Anthropic, OpenAI, and SpaceX over an 18-month window will fundamentally test public market appetite. These entities have compressed decades of corporate scaling into mere years, achieving multi-trillion-dollar scale at unprecedented velocities. While public equity markets successfully absorbed the market capitalization of SpaceX, the broader market implications will hinge on how public investors price subsequent tiers of enterprise software and artificial intelligence companies.
Ultimately, the cyclical nature of the venture capital asset class—characterized by LPs alternating between prolonged capital retraction and frantic market entry—remains an immutable feature of private markets. By maintaining rigorous portfolio reviews, balancing check sizes across economic cycles, and relentlessly prioritizing liquidity alongside visionary founder partnerships, Insight Partners continues to navigate the complexities of the modern technological revolution.